Estamos Mas Cerca de Ti Con Presencia Internacional
Nuestras Oficinas Internacionales
[freeworldhtml5map id="0"]
Client Testimonials
What Our Clients Are Saying
Carolina López
“Qkapital help us through every step of our condo buying process. Their dedication to their customers is outstanding.
They truly cared about our needs and always kept us informed. I couldn’t ask for better service! I highly recommend Them.”
Sebastián Ramírez
“Great experience! Everyone from the organization I worked with was very attentive.
Anything I needed or had questions on was answered within minutes. Would work with this group again! Thank you.”
Jorge Cury
I highly recommend QKapital for mortgage loans, Ricardo Viera my advisor is a very professional and trained person to advise you and give you the best options.
Always looking for solutions to the requirements of banks. Thanks QKapital.
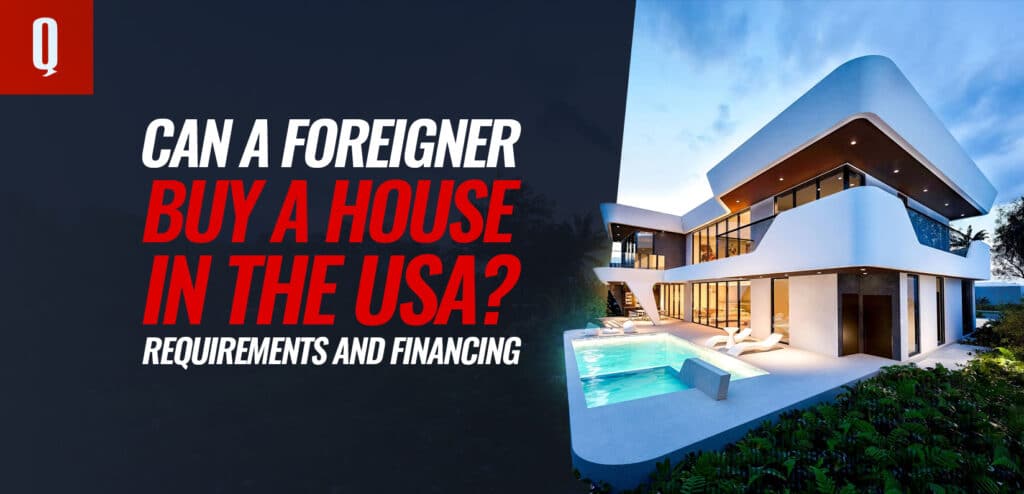
Yes, a foreigner can buy a house in the United States. There is no citizenship or residency requirement to purchase US real estate, and no law restricts foreign nationals from owning property in almost every state, Florida and Texas included. What foreign buyers actually need is a financing path built for their situation, since most conventional mortgage programs assume a US credit history and US income that international buyers don't have.
A "no doc" mortgage doesn't mean no documentation at all — it means no income documentation in the traditional sense of pay stubs, W-2s, or tax returns. Lenders still verify credit, assets, the property, and the borrower's identity; what changes is how income gets confirmed, usually through bank statements, a lender's cash flow analysis of the property (for investment purchases), or the borrower's asset balances.
An asset depletion loan lets a borrower qualify for a mortgage using savings, investments, and retirement accounts as income, instead of pay stubs or tax returns. The lender divides the borrower's total qualifying assets by a set number of months — commonly 360, matching a 30-year term — to produce a monthly income figure used in underwriting.
Request a Call Back
Please fill out the form and press the submit button.
We will get back to you as shortly as possible.
By providing your phone number, you consent to receive marketing text messages from Qapital at the mobile number provided using an automatic telephone dialing system. By opting in, you agree to receive messages from Qapital. Message and data rates may apply. Reply STOP to unsubscribe from our messages. For more information, please review our Privacy Policy.